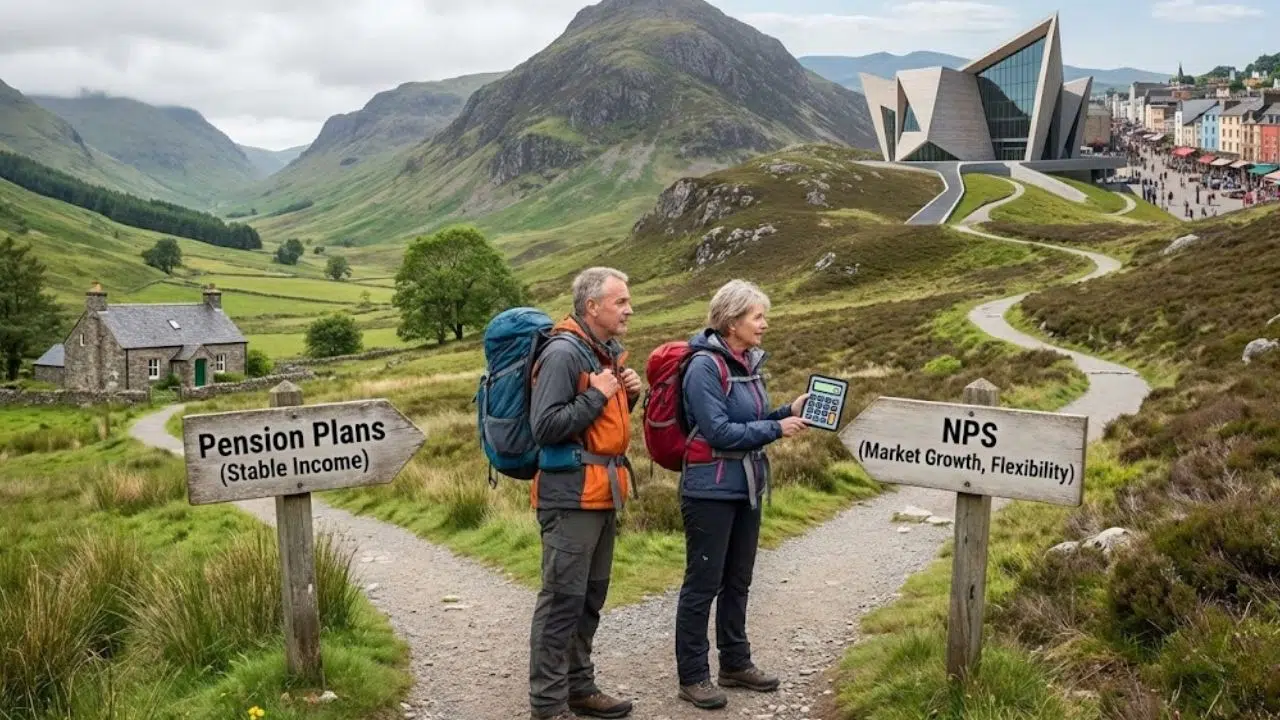
A pension plan and the National Pension System are both built for retirement, but they solve different problems. One is usually designed to give you a predictable pension-style income with clearer guarantees. The other is designed to help you build a retirement corpus through market-linked investing and then convert a part of it into pension at exit.
Pension plans in India
In most cases, a pension plan refers to a retirement product that helps you accumulate money and later receive a pension income, often through an annuity. It behaves like a structured savings plan with retirement lock-ins, payout rules, and built-in discipline.
NPS
It is a regulated retirement system where you contribute over time, invest across asset classes, and build a retirement corpus. In December 2025, PFRDA amended exit and withdrawal rules, including higher lump-sum limits and new phased-withdrawal options for certain slabs, plus higher continuation age limits.
The Differences
If you want the “best” choice, stop thinking in terms of one winner and start thinking in terms of what you need guaranteed versus what you want to grow.
1) Return potential vs certainty
- A typical pension plan often prioritises predictability and smoother outcomes. You usually sacrifice some return potential for stability.
- NPS can offer higher long-term growth potential because it is market-linked, but your corpus value will fluctuate with markets.
If you want growth and you can stay invested through bad years, NPS usually fits better. If you want steadier outcomes, a pension plan can feel easier to live with.
2) Costs and transparency
- Some pension plan structures may have layered costs, such as allocation charges, policy administration, and annuity conversion effects.
- NPS is generally positioned as cost-efficient and rule-driven, with clearer investment buckets and oversight through the NPS ecosystem.
3) Liquidity and withdrawal flexibility
- A pension plan typically has tighter lock-ins and more restrictions on partial access.
- NPS allows partial withdrawals with limits, and the rules specify how many times and how much you can take out under permitted conditions. For example, partial withdrawal is allowed up to 25% of your own contributions and up to three times during the tenure, subject to conditions.
4) How much money you can take at retirement
- For many non-government NPS subscribers at normal exit, the lump-sum limit has moved up to 80%, with at least 20% going to annuity, replacing the older 60% and 40% structure in those categories.
- Certain amendments in 2025 also introduced slabs and options like Systematic Unit Redemption for certain corpus ranges, and increased the entry and exit age limits up to 85 years in the revised framework.
With a pension plan, the pension income is often the centre of the design, so the “how much lump sum” query depends heavily on the product’s payout rules and annuity structure.
NPS has become more flexible for many non-government subscribers after the December 2025 amendments, especially around lump-sum withdrawal limits and phased withdrawal options. A pension plan still makes sense when your priority is a steadier income-style outcome and a structured savings plan discipline. Use an NPS calculator to pressure-test your numbers, then choose the plan that you can fund consistently without losing sleep.
Taxation
Tax should not be the only reason you pick a retirement product, but it can improve outcomes if you are consistent.
- NPS has well-known deductions, including the additional deduction under Section 80CCD(1B) up to Rs. 50,000 for eligible contributions, and it is commonly stated as available under the old tax regime.
- NPS also has stated tax treatment for eligible partial withdrawals up to a limit on self-contribution withdrawals under specified conditions.
A pension plan may also offer tax advantages depending on the structure and prevailing tax rules, but the exact benefit depends on the way the plan is designed and your choice of tax regime.
Using an NPS calculator
An NPS calculator is useful because it forces you to input three things you cannot escape.
- Your monthly contribution.
- Your expected rate of return assumption.
- Your retirement age and expected annuity share at exit.
Run the NPS calculator with conservative and optimistic return assumptions. If the conservative result still meets your target retirement income, NPS becomes an easier choice. If the result looks too dependent on optimistic returns, you either increase contributions or consider a more certainty-first pension plan approach for the income source.
Choose the best plan for you using these quick rules:
- Pick NPS if you want long-term growth, you can stay invested for 10 to 25 years, and enjoy the revised flexibility at exit.
- Pick a pension plan if you want stronger predictability in how retirement income is shaped, and if you prefer a structured savings plan over market-linked swings.
- Consider using both if your goal is balance, where NPS builds growth and a predictable pension product covers essential monthly expenses.
Tax exemptions are as per applicable tax laws from time to time.