A low CIBIL score, also known as your credit score, can pose challenges when seeking a personal loan. Your CIBIL score is crucial in determining your creditworthiness. However, low CIBIL scores don’t mean you’re out of options. With the right approach and strategies, securing a personal loan is possible even with a less-than-ideal credit history. In this guide, we’ll explore five key tips to help you understand the process and improve your chances of getting an urgent personal loan.
Understand Your CIBIL Score and Credit Report
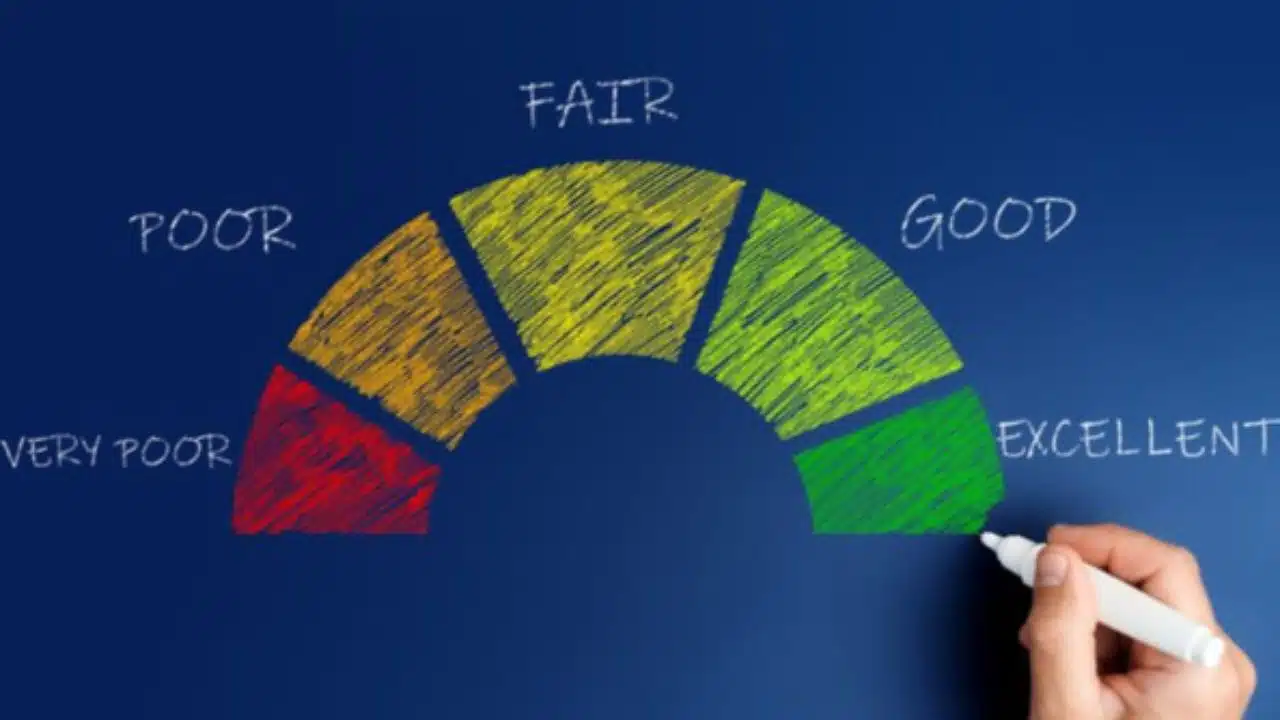
The first step to securing a personal loan with a low CIBIL score is understanding where you stand. Your CIBIL score reflects your creditworthiness and ranges from 300 to 900. A score below 600 is considered low and may indicate poor financial management. Begin by accessing your credit report to review your credit history, outstanding debts, and any discrepancies affecting your score. Understanding the factors contributing to your low CIBIL score will help you devise a plan to improve it.
Take Steps to Improve Your CIBIL Score
Improving your CIBIL score is critical in enhancing your creditworthiness and increasing your chances of securing an urgent personal loan. By taking proactive measures to strengthen your credit profile, you demonstrate to lenders that you are a responsible borrower capable of managing your finances effectively.
The first and most crucial step in improving your CIBIL score is to ensure timely payments of your bills and EMIs. Payment history accounts for a significant portion of your CIBIL score, making paying all your obligations on time essential. Late payments can significantly damage your score and signal to lenders that you may be a risky borrower. Set up automatic payments or reminders to ensure you never miss a due date and establish a track record of consistent, on-time payments.
Another factor that heavily influences your CIBIL score is your credit utilisation ratio, which measures the amount of credit you are using compared to your total available credit limit. Aim to keep your credit utilisation ratio below 30% to demonstrate responsible credit management. Avoid maxing out your credit cards or carrying high balances, as this can indicate financial instability to lenders. Consider paying down existing balances or requesting a higher credit limit to reduce your utilisation ratio and improve your cibil score.
Furthermore, avoid applying for multiple credit lines simultaneously, as each credit inquiry can temporarily lower your score. Lenders may interpret numerous credit inquiries within a short period as a sign of financial distress or desperation for credit, potentially harming your chances of loan approval. Instead, consider your borrowing needs carefully and only apply for credit when necessary.
Regularly monitoring your credit report is crucial for identifying any errors or inaccuracies dragging your score down. Review your credit report from all major credit bureaus and dispute any discrepancies promptly. Correcting errors on your credit report can significantly increase your score and improve your overall creditworthiness.
Explore Alternative Lenders
Traditional banks and financial institutions may have stringent criteria for personal loan approvals, especially for individuals with low CIBIL scores. In such cases, alternative lenders such as non-banking financial companies (NBFCs) like SMFG India Credit should be considered. These lenders often have more flexible eligibility criteria and may be more willing to extend credit to borrowers with imperfect credit histories.
Opt for a Lower Loan Amount
Consider requesting a lower loan amount when applying for a personal loan with a low CIBIL score. Lenders may be more willing to approve smaller loan amounts as they pose less risk compared to larger loans. By opting for a lower loan amount, you demonstrate responsible borrowing behaviour and increase your chances of approval. Additionally, a smaller loan amount means lower monthly instalments, making it easier to manage repayment obligations and improve your credit score.
Conclusion
Securing a personal loan with a low CIBIL score may require patience, diligence, and strategic planning. By understanding your credit situation, improving your CIBIL score, exploring alternative lenders, and opting for a lower loan amount, you can increase your chances of getting an urgent personal loan. Remember to borrow responsibly and prioritise timely repayments to rebuild your credit history and financial stability in the long run.