One loan form, and suddenly your phone won’t stop ringing with offers you can’t compare. For most owners, Lendio is the best of the business loan marketplaces for comparing offers, and SBA Lender Match is the best free start for SBA loans.
Below: a comparison chart, real flaws for all nine, and a cost cheat sheet.
Quick Comparison: Business Loan Marketplaces for Comparing Offers
Here’s the short version. None of these platforms lends you money directly except where noted, and all of them let you see options before a hard credit pull.
| Platform | Cost to Use | Network Size | Best For | Biggest Flaw |
|---|---|---|---|---|
| Lendio | Free | 75+ lenders | Most small businesses | Heavy follow-up calls |
| SBA Lender Match | Free | 800+ SBA lenders | Cheapest SBA loans | No side-by-side offers |
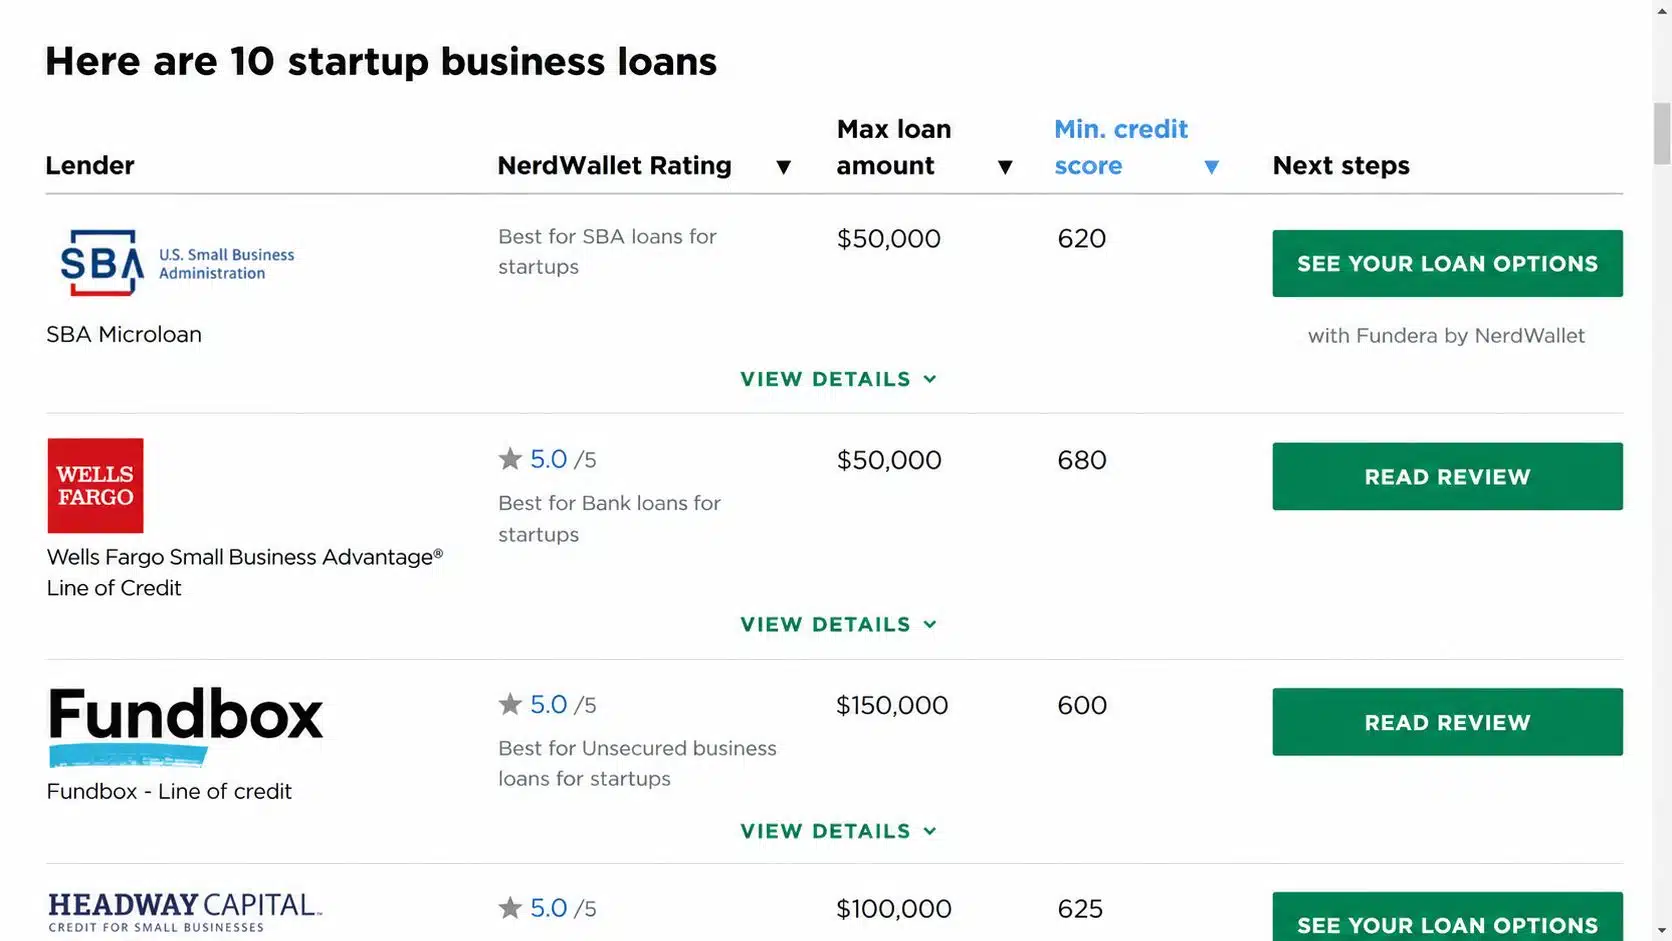
| Fundera (NerdWallet) | Free | Not published | Loans + cards in one place | Data shared with partners |
| Nav | Free; paid plans are $39.99–$74.99/mo | Not published | Fixing credit first | Best tools sit behind a paywall |
| SmartBiz | Free to apply | Bank partners + its own bank | SBA 7(a) up to $500K | Needs 2+ years in business |
| LendingTree | Free | 300+ (all loan types) | Wide net, fast | Lead-selling complaints |
| Biz2Credit | Free to apply | Own loans + partners | Established, higher-revenue firms | High revenue minimums |
| Lendzi | Free | 60+ lenders | Hands-on loan officers | Rates and fees not disclosed |
| Lantern by SoFi | Free | Smaller network | Quick prequalified quotes | Fewer offers |
Key takeaway: run at least two platforms. One commercial marketplace and SBA Lender Match will cover most owners.
How These Platforms Make Money (and Why Your Phone Rings)
Most business loan marketplaces for comparing offers are free because lenders pay them. Lendio earns referral fees from its lenders, and Fundera has been reported to earn a commission of roughly 2% to 5% on funded loans.
Here’s the catch: that model rewards a closed deal, not your cheapest deal. So expect a “funding specialist” call within hours, and expect pressure toward whatever closes fastest.
- Soft pull: used to match you. It doesn’t hurt your score.
- Hard pull: usually happens when you formally apply with one lender.
- Your data: often shared with partners. Read the consent box before you click.
The 9 Best Business Loan Marketplaces for Comparing Offers
1. Lendio — Best Overall
Lendio connects you with 75+ lenders through one application that takes about 15 minutes. It covers SBA loans, term loans, lines of credit, equipment financing, invoice financing and merchant cash advances.
Picture this: you run a two-year-old landscaping business doing $15,000 a month. Lendio can show you a line of credit, an equipment loan and an SBA option in the same week. Few marketplaces match that breadth.
Real flaws owners complain about:
- Lots of marketing calls and emails after you apply.
- Newer or low-revenue businesses may see mostly merchant cash advance offers, which cost far more.
- Some borrowers report hard inquiries from lenders they never picked.
Who Should Skip This: owners with strong credit and two-plus years of clean financials. A direct bank or credit union may beat any marketplace rate.
2. SBA Lender Match — Best Free Option for SBA Loans
This is the government’s own matching tool, and it’s free. You answer a few questions in as little as five minutes, and SBA sends a summary of interested lenders about two business days later. More than 800 SBA-approved lenders take part across all 50 states.
The best part? Nobody’s earning a referral fee off you. These are banks, credit unions and CDFIs that already offering SBA-backed loans.
Real flaws:
- It’s not a loan application. You still apply with each lender separately.
- There’s no guarantee anyone responds, and you won’t see offers side by side.
- It’s not for disaster loans.
Who Should Skip This: anyone who needs cash this week. SBA loans can take weeks.
3. Fundera by NerdWallet — Best for Loans and Credit Cards Together
NerdWallet bought Fundera in 2020, and it now operates under the NerdWallet brand. You can compare business loans, business credit cards and other products from one account without a hard pull to start.
Real flaws:
- It doesn’t publish how many lenders see your file.
- Your consent covers sharing data with NerdWallet and its partners.
Who Should Skip This: owners who want to control exactly which lenders contact them.
Nav is a credit dashboard with lender matching attached. The free plan shows basic business credit ranges and one personal Experian score, while paid plans run $39.99, $49.99, and $74.99 a month.
Now, you might be wondering, why pay for a marketplace? You usually shouldn’t. Nav’s value is seeing what lenders see before you apply, so you don’t collect rejections.
Real flaws:
- The deeper reports and lender discounts are paid features.
- Applying for a loan or card through Nav can trigger a hard pull.
Who Should Skip This: owners with strong credit who just need quotes.
5. SmartBiz — Best for Small SBA 7(a) Loans
SmartBiz focuses on SBA 7(a) loans, and its site lists amounts from $30,000 to $500,000. In 2025, it acquired Centrust Bank and became SmartBiz Bank, N.A., so it can now lend directly as well as route you to partner banks.
Real flaws:
- You need more than two years in business, and most products want fair-to-good credit.
- SBA paperwork is still SBA paperwork. Approval isn’t instant.
Who Should Skip This: startups and anyone needing funds in days.
6. LendingTree — Best for Casting a Wide Net
LendingTree’s network tops 300 lenders, but that count covers mortgages, auto and personal loans too. It’s unclear how many fund business loans.
On the flip side, the complaints are consistent. Users describe a flood of calls, texts and emails right after submitting a form.
Real flaws:
- Aggressive follow-up from partner lenders.
- Lender requirements can be vague until you’re deep in the process.
Who Should Skip This: anyone who hates sales calls.
7. Biz2Credit — Best for Established, Higher-Revenue Businesses
Biz2Credit is a hybrid. It lends directly and can also match you with partner lenders if its own products don’t fit.
Real flaws:
- Many products want around $250,000 in annual revenue.
- Fees can be hard to pin down until you get an offer.
Who Should Skip This: newer businesses or anyone under $100,000 a year.
8. Lendzi — Best for Hands-On Loan Officers
Lendzi, founded in 2020, works with 60+ lenders and gets strong reviews for its loan officers. Prequalification uses a soft credit check.
Real flaws:
- Rates and fees aren’t posted on the site.
- Only a handful of its lenders are named publicly.
Who Should Skip This: owners who want rates in writing before talking to anyone.
9. Lantern by SoFi — Best for Quick Prequalified Quotes
SoFi runs this marketplace through SoFi Lending Corp., which doesn’t make the business loans itself. SoFi gets paid if you take a product through it.
Real flaws:
- A smaller network means fewer offers than Lendio.
- Partner details are thin.
Who Should Skip This: owners who want the widest possible field of lenders.
How to Compare Offers Without Getting Burned
That brings us to the biggest mistake people make: comparing the payment instead of the total cost.
Picture this: you take a $20,000 merchant cash advance with a 1.3 factor rate. You’ll repay $26,000, so the cost is $6,000. If you pay it off in six months, that’s far more expensive than “30%” sounds, because you paid it in half a year.
Use this checklist on every offer:
- Total repayment amount, in dollars.
- Every fee: origination, draw, servicing and prepayment.
- Payment frequency. Daily and weekly payments hit cash flow hard.
- APR or estimated APR, where your state requires it.
Several states now require lenders to show this math. California and New York require an APR-style disclosure, while states like Utah, Virginia, Florida and Georgia use total-cost disclosures instead. Rules and dollar limits vary, so check your state.
Not sure which product fits? Start with this guide to business loan types, then see which business loans are expected to be popular in 2026. Before you apply anywhere, check your business loan eligibility and work on improving your approval chances.
Frequently Asked Questions (FAQs)
Do business loan marketplaces hurt your credit score?
Usually not at first. Most use a soft pull to match you, and a hard pull comes when you formally apply with a lender.
Are business loan marketplaces free?
Yes, for borrowers. Lenders pay the marketplace, and you pay the lender’s rates and fees.
Is a loan marketplace the same as a lender?
No. A marketplace matches you with lenders. SmartBiz and Biz2Credit are exceptions that also lend directly.
How fast can you get funded?
Some online loans fund in a day or two. SBA loans often take weeks.
What’s the best business loan marketplace for bad credit?
Lendio and Lendzi accept lower scores than most but expect higher rates. Nav can help you fix your credit first.
Final Thoughts
Don’t trust a single quote. Run one commercial marketplace and SBA Lender Match side by side, then compare total repayment in dollars. Used that way, business loan marketplaces for comparing offers save you time without costing you money.