In 2026, the concept of a banking app is undergoing a radical transformation. No longer just a digital ledger for checking balances, the modern banking interface has evolved into a sophisticated financial command center. The transition from reactive tools to proactive agents is driven by the need for speed, security, and extreme personalization.
For users, this means that the must-have banking app features 2026 brings to the table are designed to simplify life while maximizing wealth. From self-driving money to “invisible” security layers, these innovations are not just luxuries; they are the new standard for digital trust. As we navigate this shifting landscape, understanding these seven key features will help you identify whether your bank is leading the charge or falling behind in the global fintech race.
1. Hyper-Personalization via Agentic AI
Hyper-personalization is no longer about just seeing your name on a dashboard; it is about an app that understands your life stage and reacts to your unique financial behavior. In 2026, the must-have banking app features 2026 includes “Agentic AI,” which goes beyond simple chatbots to act as a digital concierge. This technology analyzes your spending history, upcoming obligations, and even local economic trends to offer real-time, context-aware advice. For instance, if you frequently visit a specific grocery store, the app might negotiate a custom cashback offer for you or suggest a more cost-effective alternative. This shift moves the bank from being a passive storage vault to an active partner in your daily decision-making process.
| Feature Component | Practical Benefit to User |
| Predictive Cash Flow | Forecasts your balance 30 days out to prevent accidental overdrafts. |
| Contextual Offers | Sends relevant discounts based on your current GPS location and past shopping habits. |
| Sentiment Monitoring | Adjusts the app’s complexity or offers human support when it detects user stress. |
Will AI in banking apps replace human advisors?
While AI is becoming the primary interface for daily tasks, it is not a total replacement for human expertise. Instead, it acts as a filter, handling routine inquiries and data analysis so that human advisors can focus on high-stakes emotional decisions like estate planning or complex mortgage negotiations. By 2026, the best apps will offer a “hybrid” model where the AI prepares all your data before seamlessly handing you off to a live expert via high-definition video call.
2. “Invisible” Security and Behavioral Biometrics
The era of the password and the annoying six-digit SMS code is officially coming to an end. Security in 2026 is becoming “invisible,” relying on continuous authentication through multi-modal biometrics and behavioral analytics. This means the app constantly verifies your identity based on how you hold your phone, your typing cadence, and even your unique swipe patterns. Because these traits are nearly impossible for a fraudster to replicate, the app can offer a frictionless experience while maintaining military-grade protection. If a thief steals your unlocked phone, the app will instantly detect that the user’s interaction “rhythm” has changed and will lock sensitive transactions automatically.
| Security Layer | How It Works |
| Behavioral Analytics | Monitors typing speed, screen pressure, and device tilt angle to confirm the user. |
| Continuous Auth | Background checks that happen every few seconds rather than just at login. |
| Liveness Detection | Advanced camera checks that distinguish between a live face and a deepfake or photo. |
Is biometric security actually safer than a password?
Yes, it is exponentially safer because it removes the “human error” factor. Passwords can be phished, guessed, or stolen in massive data breaches, but your unique behavioral rhythm is yours alone. Furthermore, by 2026, biometric data is typically stored as an encrypted mathematical “hash” rather than a raw image, meaning even if a bank is hacked, your actual face or fingerprint cannot be reconstructed by criminals.
3. Voice-First Banking and Natural Language Processing
Voice interaction is set to become a primary way we interact with our money by 2026. Thanks to advancements in Natural Language Processing (NLP), you can talk to your banking app just as you would to a professional teller. Instead of hunting through three sub-menus to find a specific transaction, you can simply ask, “How much did I spend on coffee this month compared to last?” and get an instant, spoken summary. This feature is particularly vital for making banking inclusive, providing easy access for the visually impaired or the elderly who might struggle with small buttons and complex screen hierarchies.
| Voice Feature | Use Case Example |
| Conversational Search | Ask “Where did that $50 charge from Tuesday come from?” for instant clarity. |
| Hands-Free Payments | Authorize bill payments or transfers while driving or cooking using voice ID. |
| Multilingual Support | Instant translation that allows users to bank in their native dialect or slang. |
Can voice banking understand different accents?
Modern NLP models are trained on billions of diverse voice samples, allowing them to understand a vast range of global accents and regional dialects. By 2026, these systems are sophisticated enough to filter out background noise in a busy cafe and still accurately identify the user’s voice print. This makes the must-have banking app features 2026 accessible to a global population, regardless of their linguistic background or technical literacy.
4. Autonomous Finance: The Self-Driving Wallet
Autonomous finance represents the ultimate evolution of the banking app—moving from a tool you “use” to a system that “runs” for you. Often called “self-driving money,” this feature allows the app to execute routine financial tasks based on your pre-set goals. It can automatically hunt for high-yield savings rates and move your excess cash there, or it can monitor your utilities and switch you to a cheaper provider when a contract ends. The goal is to eliminate “financial chores,” freeing up your mental energy for more important things while ensuring your money is always working as hard as possible.
| Autonomous Function | Value Created |
| Smart Sweeping | Automatically moves “extra” cash into investment or savings accounts daily. |
| Subscription Defense | Identifies and cancels “zombie” subscriptions you no longer use. |
| Rate Optimization | Automatically refinances small loans or switches savings to higher-rate buckets. |
What if the AI makes a mistake with my money?
To build trust, autonomous finance in 2026 operates on a “permission-based” sliding scale. You can set limits so the app handles small, routine transfers (under $100) automatically, but asks for a quick “FaceID” approval for larger strategic moves. This ensures that while the heavy lifting is automated, you always remain the final decision-maker for your major financial milestones.
5. The “Super App” Evolution and Embedded Services
Banking apps are no longer isolated silos; they are becoming the “remote control” for your entire lifestyle. The must-have banking app features 2026 include embedded services that allow you to book travel, pay for parking, or even buy a car directly within the banking interface. This “Super App” model, popular in Asia for years, is finally dominating Western markets. By bringing non-financial services like retail, insurance, and legal support into a single ecosystem, banks can offer a seamless experience where payments, loyalty points, and identity verification are all handled in one place.
| Embedded Service | Integrated Benefit |
| Travel Hub | Book flights and hotels with integrated travel insurance and instant FX rates. |
| Gig Economy Tools | Tools for freelancers to track taxes and smooth out irregular income. |
| Marketplace | A vetted “app store” for insurance, stocks, and crypto directly in the dashboard. |
Why are Western banks becoming Super Apps?
The shift toward Super Apps is driven by competition from big tech companies like Apple and Google. Traditional banks realize that if they only offer a ledger, they will lose the customer relationship to more engaging platforms. By becoming a central hub for all daily transactions—not just banking—they ensure higher user engagement and can provide better financial products based on a richer understanding of the user’s lifestyle.
6. Next-Gen Payments and Cardless Ecosystems
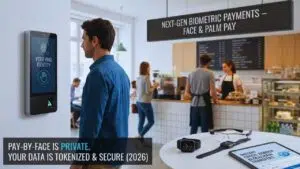
The physical plastic card is rapidly becoming a relic of the past as we move into a completely cardless ecosystem. In 2026, your banking app serves as the gateway to biometric payments where your face, palm, or even your fingerprint is your “card.” You can walk into a store, pick up an item, and pay simply by looking at a terminal that is securely linked to your bank. Furthermore, the rise of blockchain-based backends means that international payments that used to take days now happen in seconds for a fraction of the previous cost, all managed through a simple interface in your app.
| Payment Method | Innovation |
| Palm/Face Pay | Biometric verification at the terminal without needing a phone or wallet. |
| Instant Cross-Border | Using stablecoins or blockchain rails for real-time global transfers. |
| Wearable Sync | Managing spending limits and permissions for smart rings, watches, and glasses. |
Is Pay-by-Face a privacy risk?
Privacy is a top concern, but 2026 regulations like the “Digital Identity Act” ensure that your biometric data is tokenized. The store never actually “sees” or stores your face; they receive an encrypted token from your bank that says “identity verified.” This makes biometric payments significantly more private than traditional credit cards, which often leak your name and card number to every merchant you visit.
7. Sustainable Banking and Carbon Tracking
As environmental concerns move to the forefront of consumer consciousness, sustainable banking features have become essential. Modern apps now include carbon footprint tracking, which automatically calculates the environmental impact of every purchase you make. If you buy a flight, the app shows you the CO2 impact and offers a one-tap option to offset that footprint by supporting certified reforestation projects. This turns your daily spending into an opportunity to align your finances with your personal values, a feature that is particularly popular among Gen Z and millennial users.
| Green Feature | How It Helps the Planet |
| Carbon Ledger | Visualizes the CO2 footprint of your shopping habits in real-time. |
| ESG Filter | Allows you to block your deposits from being lent to fossil fuel or tobacco industries. |
| Green Rewards | Offers lower interest rates or cashback for “green” purchases like EV charging. |
Why do banks care about my carbon footprint?
Banks have realized that climate risk is a financial risk. By helping users track and reduce their carbon footprint, banks are encouraging a shift toward a more sustainable economy that is more stable in the long term. Additionally, offering these tools is the most effective way for banks to attract the “conscious consumer,” a demographic that increasingly chooses where to put their money based on a company’s environmental and social impact.
Final Thoughts
As we look toward the future, it is clear that the must-have banking app features 2026 prioritize a blend of autonomy, security, and human-centric design. The best apps will no longer just respond to your commands; they will anticipate your needs, protect you from invisible threats, and help you live a more sustainable life. Whether it is the convenience of a self-driving wallet or the security of behavioral biometrics, these tools are redefining what it means to be “financially empowered.” If your current banking experience feels like a chore, it may be time to seek out a platform that is ready for the world of 2026.