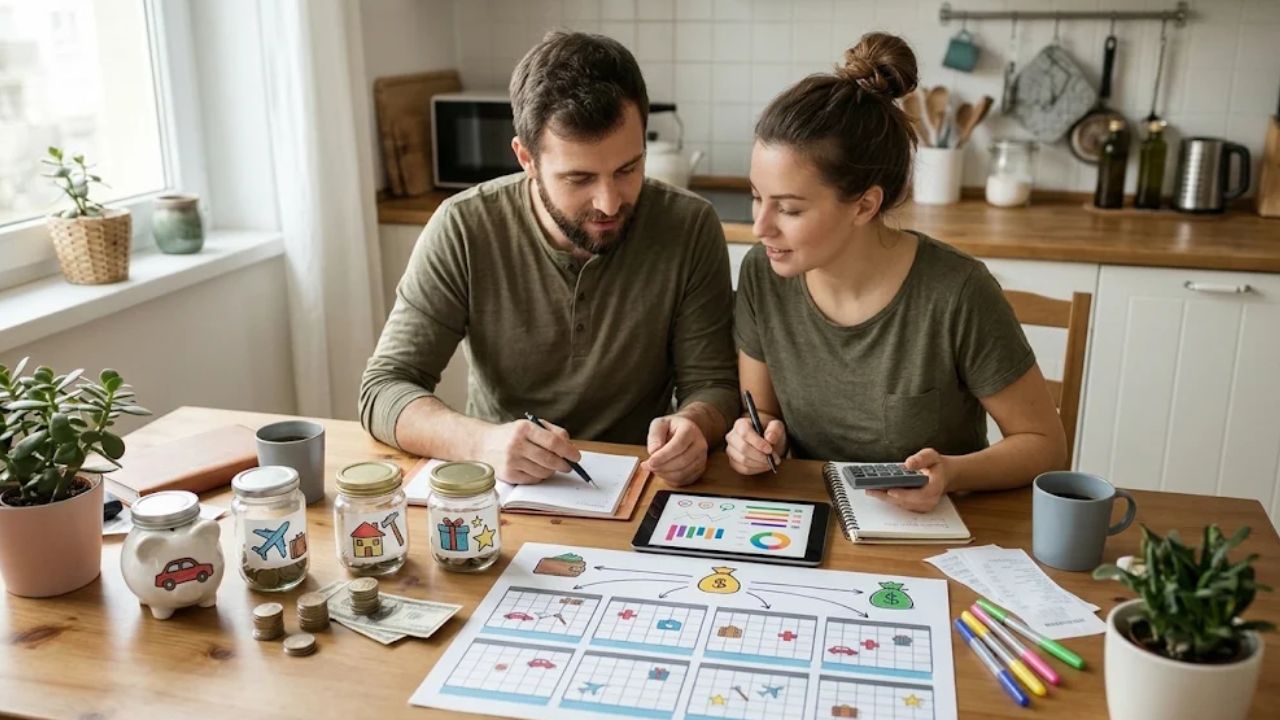
A budget can cover every monthly bill and still feel repeatedly disrupted. Annual renewals, gifts, travel, and repairs arrive less frequently, but they still need a place in the plan.
Couples can make these expenses easier to discuss by looking beyond the current month.
Review the previous year
Look through statements and calendars for costs that do not appear every month. Include annual subscriptions, seasonal travel, celebrations, and routine maintenance.
Distinguish predictable expenses from genuine surprises. An annual renewal has a date and an approximate cost. An unexpected repair is less certain.
That distinction helps determine whether to save toward a known bill or keep more general flexibility.
Turn a future cost into a monthly amount
For an illustrative expense of $600 due in six months, setting aside $100 a month would cover the target.
Use the time remaining until the payment is due. Dividing by twelve only works when you actually have twelve months to prepare.
If the required amount does not fit, discuss the options early: reduce the cost, change the timing where possible, or adjust another part of the budget.
Agree on ownership and access
Choose where the money will be recorded or held and who will make the payment. A named savings category can help distinguish money reserved for a future bill from money available today.
Both partners should understand what the balance represents. Otherwise, one person may see spare cash while the other sees next month’s insurance payment.
Separate planned purchases from emergencies
An expense does not become an emergency simply because it is paid infrequently. A yearly membership, a planned trip, or a routine service appointment can usually be identified ahead of time, even when the final price is uncertain.
Make a short calendar for the next twelve months. Write down when each known expense is likely to occur and whether you already have money reserved for it. The calendar helps both partners see why a month with few regular bills may still require saving.
For a fictional couple, the list might include $360 for an annual renewal, $500 for a planned family visit, and an estimated $240 for routine maintenance. Each item has a different deadline, so the monthly amount depends on how much time remains. Keep the estimates separate rather than combining everything into a single unexplained savings target.
Some future costs cannot be estimated closely. In that case, record a reasonable provisional figure and the information needed to improve it. A quote, a renewal notice, or a confirmed travel date can give the couple a reason to revisit the number. The uncertainty should remain visible instead of disappearing behind a precise-looking total.
Agree on how reserved money can be used
Money set aside for several purposes can become confusing when it sits in one account. A simple record of categories can help, provided the total allocated does not exceed the actual money available.
Suppose a balance of $900 includes $400 for a renewal and $500 for travel. If the couple takes $200 from it for another purchase, the record needs to show which goal has changed. Otherwise, both original targets may still appear fully funded even though the account no longer supports them.
Discuss whether money can move between categories without a conversation. Small adjustments may be easy to agree on, while using funds reserved for a near-term bill can have a larger effect. The rule should reflect the deadlines and the household’s ability to replace the money.
When a planned expense is paid, record the actual amount and consider the next cycle. A yearly cost may require a smaller monthly contribution once the full year is available, but the target may also have changed. Keep the new estimate grounded in the information you have.
Review unused categories occasionally. A subscription you cancelled or a trip you no longer plan should not continue attracting contributions automatically. Releasing that money through an explicit decision keeps the budget aligned with the couple’s current plans rather than last year’s calendar.
Keep the record current so that both partners can see any reassignment.
Update estimates as information improves
A renewal quote or travel booking can change the target. Revise the plan when you have a firmer figure rather than waiting until the bill is due.
Nevlin’s article on how to manage money as a couple provides a related starting point for shared money conversations. Couples can also explore budgeting concepts through Nevlin’s financial education resources.
Planning for irregular costs gives future expenses a place in today’s decisions.