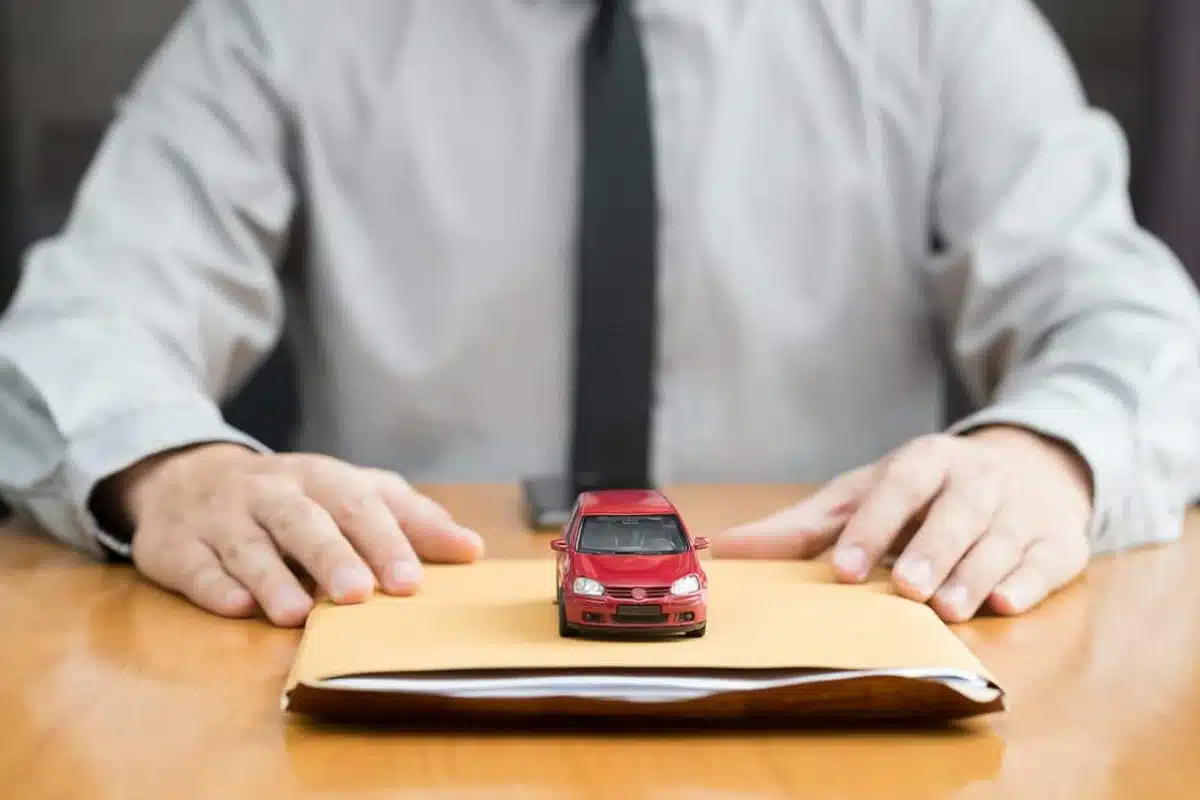
What is a title loan? A title loan is a loan that is secured by the borrower’s car. The borrower gives the lender the title to their car as collateral for the loan. The lender holds onto the title until the loan is paid off. If the borrower defaults on the loan, the lender can repossess the car.
How do title loans work? Title loans are a type of secured loan, which means that the loan is secured by collateral. In this case, the collateral is the borrower’s car. The lender holds the title to the car as collateral for the loan. The borrower pays the lender interest on the loan. The lender will use the Kelly Blue Book to determine the wholesale value of the vehicle.
What are the benefits of title loans? Title loans are beneficial because they offer a quick and easy way to get cash, you can get the maximum cash with title loans. They are also convenient because you can use your car title as collateral. This means that you can keep driving your car while you repay the loan.
What are the risks of title loans? One of the biggest risks is that if you can’t repay the loan, the lender can repossess your car. This can leave you without a way to get to work or school, and can make it difficult to meet other obligations. Another risk of not having a car is that you are reliant on others for transportation. This can be difficult if you have a job that requires you to work odd hours or if you live in a rural area. Not having a car can also limit your social life. You may have to rely on public transportation, which can be expensive and time-consuming. You may also miss out on opportunities to socialize with friends or go to events because you can’t drive.
Title Loan Information
How much can you borrow with a title loan? You can usually borrow anywhere from $100 to $50,000, depending on the value of your car and your state’s laws. You want to get the max cash on your title loan, with the lowest interest. The amount that you can borrow will depend on the value of your car and the laws in your state. In some states, you may be able to borrow up to $50,000, while in others, the limit may be lower. The amount you’re able to borrow may also depend on factors such as your income, employment history, and credit score. In general, the better your financial situation, the more money you’ll be able to borrow. The title loan company wants to make sure that you can make your monthly payments.
What is the interest rate for a title loan? The interest rate for a title loan can vary depending on the lender. Some lenders may charge a higher interest rate for a title loan, so it is important to shop around and compare rates before taking out a loan. There are many factors to consider when taking out a title loan, and it is important to compare rates from different lenders before making a decision. Some things to consider include the interest rate, the length of the loan, and any fees associated with the loan. In addition, it’s important to think about whether you’ll be able to afford the monthly payments, and whether you’re comfortable with the idea of having debt. It’s also worth considering whether you could get a better deal by refinancing later on. If you’re not sure whether you’ll be able to make your payments on time, it’s worth considering whether you could get a better deal by refinancing later on.
Title Loan Terms
What are the repayment terms for a title loan? Most title loan companies will give you a repayment plan that is anywhere from 30 days to one year. This is plenty of time for you to come up with the money to pay off the loan. However, if you do not think that you will be able to make the payments, you should contact the lender and try to work out a different arrangement. Perhaps you can extend the loan for a longer period of time, or make smaller monthly payments. If you are having trouble making the payments, the lender may be willing to work with you to come up with a new payment plan that works better for your budget. They may also be willing to lower your interest rate or extend your repayment term.
What happens if you can’t repay a title loan? If you can’t repay your title loan, the lender may take your car. This is because the car is used as collateral for the loan. If you can’t repay the loan, the lender has the right to take your car. All title loan lenders need to be incompliance with the CFPB.
How do I get a title loan? You can get a title loan by going to a lender and filling out an application. The lender will then review your application and determine if you are eligible for a loan. If you are approved, the lender will give you the loan amount and you will be responsible for repaying the loan, with interest. The interest rate will be determined by the lender, and may be fixed or variable. The loan term will also be determined by the lender, and may be anywhere from a few months to several years.