Your 20s are an exciting time filled with new experiences, independence, and the freedom to make your own decisions.
This decade is often a defining period for your financial future, laying the foundation for habits and decisions that can impact you for years to come.
Unfortunately, many young adults make financial missteps that can hinder their growth or create unnecessary setbacks.
Here, we’ll explore ten common financial mistakes to avoid in your 20s, giving you a roadmap for smarter spending, saving, and planning to ensure a secure financial future.
1. Ignoring Budgeting and Spending Without a Plan
One of the biggest pitfalls in your 20s is neglecting to create a budget.
Budgeting may sound restrictive, but it’s actually one of the best tools to help you make informed financial decisions and prevent unnecessary debt.
A budget allows you to see where your money is going, helping you control spending and align it with your financial goals.
Why Budgeting Matters?
- Builds Financial Awareness: Knowing exactly where your money goes each month provides clarity on spending patterns, making it easier to identify unnecessary expenses and areas where you can cut back.
- Helps Prioritize Goals: With a budget, you can prioritize saving for emergencies, retirement, and other financial goals, ensuring your money supports both short-term needs and long-term ambitions.
- Prevents Impulse Spending: When you have a budget, you’re less likely to make impulse purchases that don’t fit your financial plans. Budgeting teaches you to delaygratification and spend thoughtfully.
Creating a budget doesn’t have to be complicated.
Start with a simple spreadsheet or use a budgeting app to track your income and categorize expenses like rent, food, entertainment, and savings.
Remember, a budget isn’t about limiting your life but about ensuring you’re making intentional financial choices that benefit your future.
2. Accumulating Credit Card Debt
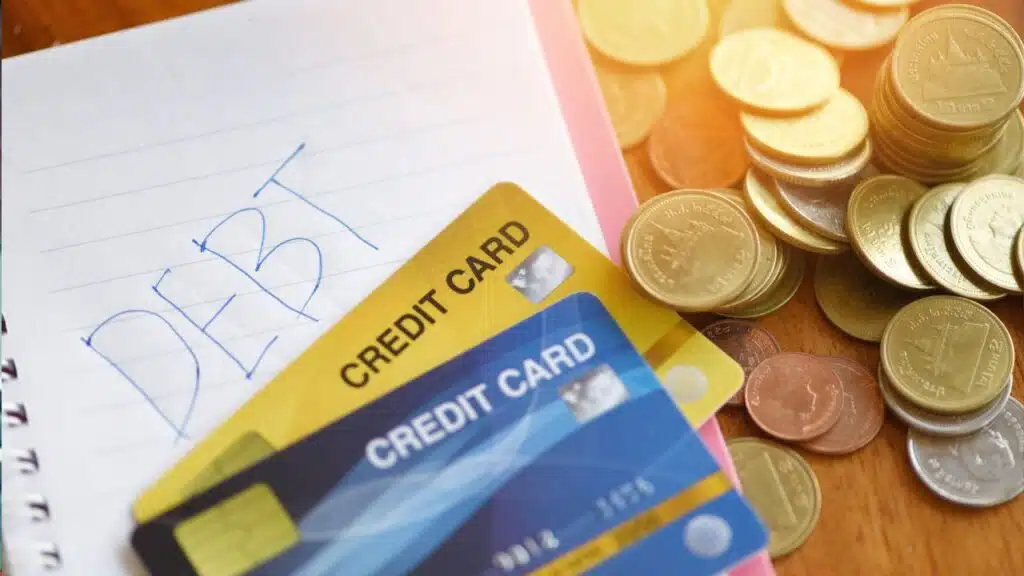
Credit cards can be a useful tool for building credit, but they also come with high-interest rates that can lead to mounting debt if not used responsibly.
Many young adults find themselves in credit card debt, often from overspending or relying on credit to finance a lifestyle beyond their means.
Dangers of Credit Card Debt
- High-Interest Rates Compound Debt: Credit card interest rates are usually between 15-25%, and if you only make minimum payments, the interest quickly adds up, making it harder to pay off your balance.
- Negative Impact on Credit Score: High credit card balances and missed payments hurt your credit score, which affects your ability to secure loans, rent apartments, or even get certain jobs.
- Long-Term Financial Stress: Credit card debt can take years to pay off, especially if you’re only making minimum payments. This debt restricts your ability to save, invest, and achieve other financial goals.
To avoid falling into credit card debt, try to pay off your balance in full each month.
Only use your card for purchases you can afford and set a spending limit to keep yourself in check.
Remember, credit cards aren’t free money—they’re a tool to build credit responsibly and should be used carefully.
3. Neglecting to Start an Emergency Fund
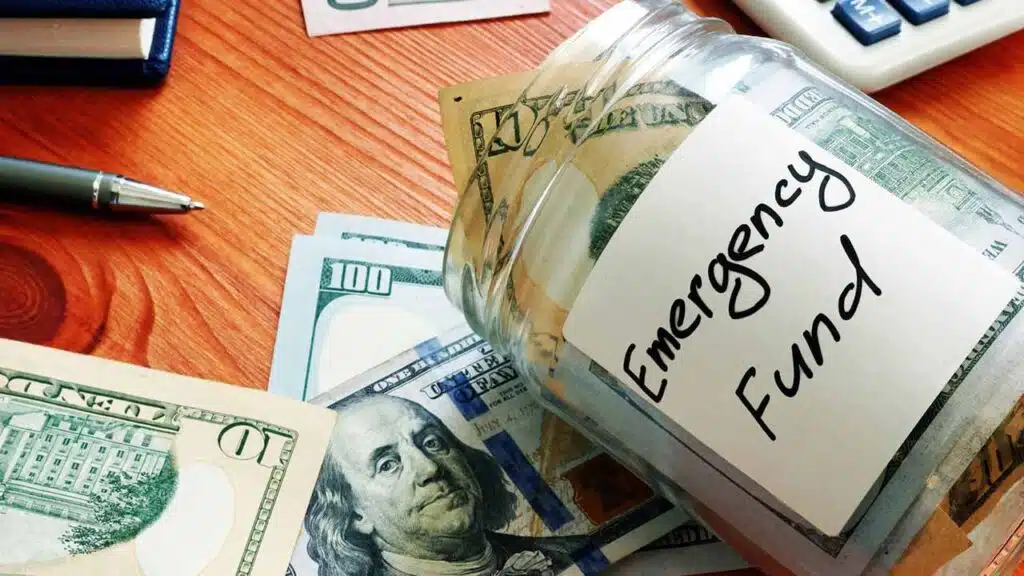
Life is unpredictable, and having an emergency fund is essential to cover unexpected expenses without going into debt.
However, many people in their 20s overlook the importance of an emergency fund, relying on credit cards or loans when unexpected costs arise.
An emergency fund provides a financial cushion, giving you peace of mind and the ability to handle life’s curveballs without financial stress.
Why an Emergency Fund is Essential?
- Protects Against Unexpected Expenses: An emergency fund can cover expenses like car repairs, medical bills, or sudden job loss, helping you avoid taking on debt.
- Reduces Financial Anxiety: Knowing you have a safety net provides financial security, reducing stress and allowing you to focus on other goals.
- Prevents Disruptions to Financial Goals: Without an emergency fund, unexpected costs can force you to dip into savings or halt contributions to retirement accounts, delaying your financial progress.
Ideally, an emergency fund should cover three to six months’ worth of expenses, but start with a smaller goal if that seems overwhelming.
Set up automatic transfers to a separate savings account and build it gradually.
Avoid using this fund for non-emergencies, as its primary purpose is to protect you in genuine crises.
4. Skipping Health and Disability Insurance
It’s common for young people to skip health and disability insurance, assuming they don’t need it.
However, medical emergencies and accidents can happen at any age, and without insurance, you could face overwhelming medical expenses.
Health and disability insurance protect your finances and ensure you’re covered in case of unforeseen medical needs.
The Importance of Health and Disability Insurance
- Protects Against Medical Bills: Health insurance helps cover doctor visits, hospital stays, and treatments that can be costly without coverage. Medical bills are one of the top causes of bankruptcy, making insurance essential for financial security.
- Income Protection: Disability insurance provides income if you’re unable to work due to illness or injury, which can be crucial for covering your expenses during recovery.
- Long-Term Financial Health: Without health insurance, even minor medical issues can lead to significant bills that deplete savings or push you into debt.
If you’re employed, check if your company offers health and disability insurance.
Many employers offer coverage at a lower cost, making it an affordable option.
If not, consider finding an individual plan that fits your budget and provides essential coverage.
5. Failing to Start Saving for Retirement Early
Retirement may seem far away, but the earlier you start saving, the more you benefit from compound interest, which allows your money to grow over time.
Waiting too long to start saving can significantly impact your retirement funds, making it one of the biggest financial mistakes to avoid in your 20s.
Benefits of Early Retirement Savings
- Harnessing Compound Interest: Starting early allows your investments to grow exponentially over time. Even small contributions add up, making it easier to reach retirement goals with minimal effort.
- Tax Advantages: Contributing to retirement accounts like an RRSP or 401(k) provides tax benefits, allowing you to save for retirement while reducing your tax burden.
- Achieving Financial Independence: Building a retirement fund early contributes to financial independence, giving you freedom and security in later years.
Even if you can only contribute a small amount, prioritize retirement savings.
Consider setting up automatic contributions to your retirement account to make saving consistent and effortless.
Your future self will thank you for the head start.
6. Not Setting Clear Financial Goals
Without financial goals, it’s easy to drift through life without making meaningful financial progress.
Setting clear, actionable financial goals provides direction, helping you allocate your resources effectively and stay motivated.
Why Financial Goals Matter?
- Creates Focus and Discipline: Financial goals keep you focused on what you want to achieve, making it easier to avoid unnecessary expenses and stay committed to saving or investing.
- Encourages Long-Term Planning: Goals help you think beyond the immediate, inspiring you to make choices that benefit you in the long run.
- Boosts Motivation: Goals provide a sense of purpose and accomplishment. Whether it’s paying off debt, saving for a down payment, or traveling, achieving these goals boosts your confidence.
Set both short-term and long-term financial goals.
Short-term goals might include saving for a vacation or paying off a credit card, while long-term goals could involve buying a home or investing for retirement.
Write down these goals and revisit them periodically to stay on track.
7. Overlooking the Importance of Your Credit Score
Your credit score impacts various aspects of your financial life, from securing loans to renting an apartment or even landing certain jobs.
Many people in their 20s neglect their credit score, not realizing how important it is for financial success.
Building good credit now can open doors and make future financial decisions easier.
Why Building Good Credit Matters?
- Easier Access to Loans and Mortgages: A good credit score improves your chances of securing loans or mortgages with better interest rates, saving you money in the long run.
- Better Renting and Employment Opportunities: Some landlords and employers check credit scores as part of their screening process, making good credit essential for various life goals.
- Financial Flexibility: A good credit score gives you flexibility when you need it, whether it’s financing a car, starting a business, or handling unexpected expenses.
To build good credit, pay bills on time, keep credit card balances low, and avoid opening too many accounts. Regularly check your credit report to ensure accuracy and catch any errors.
8. Not Investing or Delaying Investments
Investing can feel intimidating, especially in your 20s, but waiting too long can mean missing out on significant growth potential.
The earlier you start investing, the more time your money has to grow, allowing you to achieve financial goals faster.
Benefits of Investing Early
- Compound Growth Over Time: Investments grow exponentially through compound interest, meaning the earlier you start, the greater your wealth can grow.
- Increased Financial Security: Investing adds another income stream, providing security and a cushion for future needs.
- Wealth Accumulation: Investing is one of the best ways to build wealth. With patience and consistent contributions, even small investments can grow significantly.
Start small with accessible options, such as index funds or mutual funds, which offer diversification and lower risk.
Many online platforms now make investing easy and affordable, allowing you to begin with just a few dollars.
9. Falling for Lifestyle Inflation
Lifestyle inflation happens when you increase your spending as your income grows, often on things like dining out, vacations, or gadgets.
While it’s natural to want to enjoy your earnings, excessive lifestyle inflation can prevent you from achieving financial security.
Why Avoiding Lifestyle Inflation is Important?
- Preserves Savings and Investments: Keeping your spending in check allows you to put more money into savings or investments, which is crucial for building long-term wealth.
- Encourages Financial Discipline: Learning to live below your means is a valuable skill that helps you stay focused on bigger financial goals.
- Protects Against Financial Setbacks: Avoiding lifestyle inflation reduces the need for credit or loans to sustain your lifestyle, providing stability in case of income changes.
While it’s okay to reward yourself, make conscious spending choices.
Set limits on discretionary expenses and prioritize saving or investing any additional income rather than splurging.
10. Not Seeking Financial Advice Early On
Many people in their 20s hesitate to seek financial advice, assuming they can handle finances alone or fearing the costs.
However, consulting a financial advisor can provide valuable insights that help you avoid costly mistakes, especially as you begin earning and building wealth.
Benefits of Seeking Financial Advice
- Personalized Financial Guidance: Advisors offer strategies tailored to your specific goals, whether it’s paying off debt, building an emergency fund, or investing for the future.
- Long-Term Planning and Wealth Building: An advisor can help you create a financial plan that prepares you for major milestones and maximizes your savings potential.
- Avoiding Costly Mistakes: Advisors can provide insights and guidance to help you make informed decisions, minimizing the risk of financial missteps.
Even if a professional advisor isn’t feasible, consider using online resources, financial planning tools, or courses to educate yourself on personal finance.
The knowledge you gain will empower you to make better financial decisions.
Final Thoughts: Building Financial Success in Your 20s
Your 20s are a time of growth, learning, and laying the groundwork for a prosperous future.
By avoiding these common financial mistakes, you can set yourself on a path toward financial security, independence, and freedom.
With careful planning, discipline, and a focus on long-term goals, you can make your 20s the starting point for a financially successful life.
Remember, the habits you build today will shape your financial future—so make each decision count!