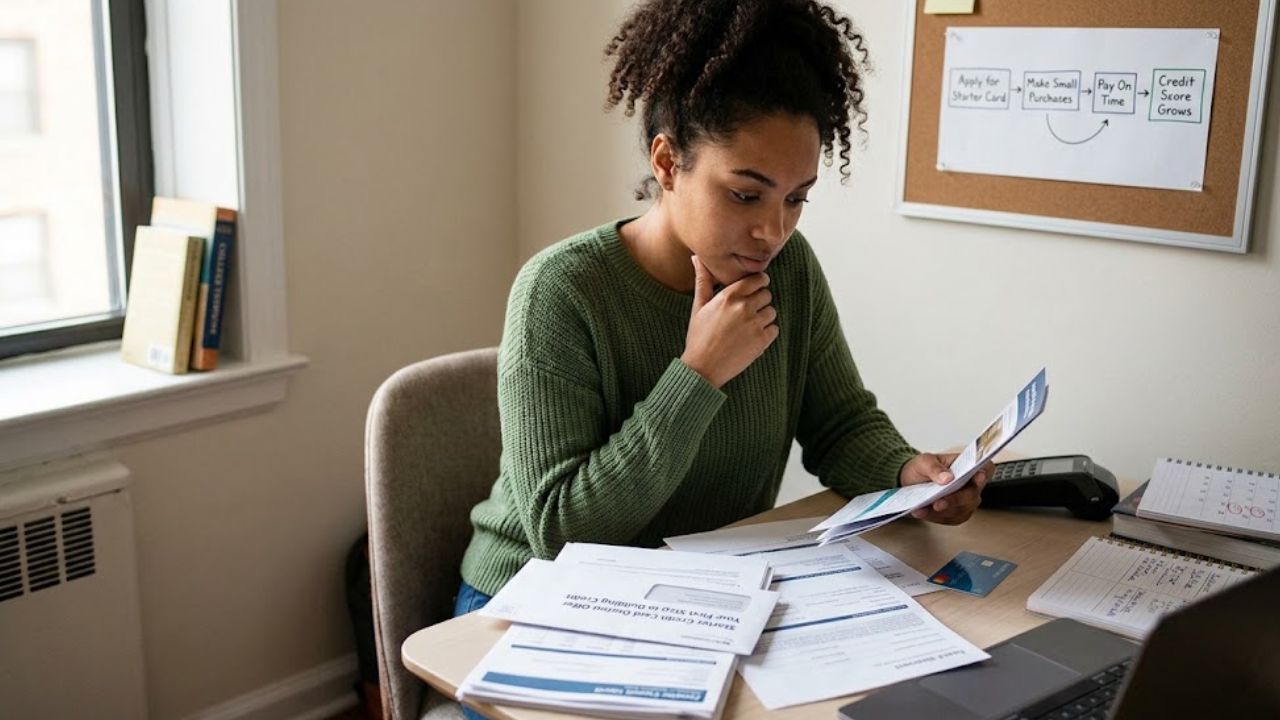
Apply for any kind of credit for the first time, and a strange contradiction shows up almost immediately. Lenders want to see a track record before extending anything meaningful, yet there’s no way to build that track record without someone extending credit in the first place.
Anyone starting from zero runs into this loop quickly, and figuring out how to break into it matters a lot more than most people realize until they’re actually stuck in it.
Why Is Having No Credit History Its Own Kind of Problem?
Because a lender has nothing to base a decision on beyond your income and whatever documents you hand over. A thin or empty credit file doesn’t mean you’re a risky borrower, it just means there’s no evidence either way.
Lenders tend to price that uncertainty cautiously rather than optimistically. Someone with no history often gets smaller amounts, higher rates, or outright rejection, not because of anything they did wrong, but simply because there’s nothing to point to yet.
What Actually Counts as a New-to-Credit Profile?
Anyone who hasn’t taken a loan or held a credit card long enough to generate a meaningful record. This includes people just entering the workforce, someone who’s always paid for everything in cash, or a person returning to active borrowing after a long gap.
The starting point looks different for each of these situations, but the underlying problem, an empty or thin file, is the same.
Where Does a Secured Credit Card Fit Into This?
Often, it’s the easiest entry point available. A card secured against a fixed deposit doesn’t require an existing credit history to get approved, since the deposit itself covers the risk for the issuer.
Using it regularly and clearing the bill in full each cycle starts generating exactly the kind of activity a credit file needs, without requiring the applicant to prove anything beyond having some savings set aside already.
Starting Small and Building From There
A modest, deliberately manageable loan can do more for a thin file than people expect. Taking a small personal loan specifically to establish repayment history, one sized comfortably within what you can actually repay without strain, creates a clean track record faster than waiting for a bigger borrowing need to come along naturally.
The goal here isn’t the loan amount itself; it’s the discipline of repaying it on schedule every single time.
Does Gold Ever Help Someone With No Credit History at All?
Yes, and this is often overlooked by people just starting out. Gold-backed borrowing generally leans on the value of the pledged asset rather than an existing credit record, which makes it accessible even to someone with an entirely empty file.
Checking what you’d qualify for through a gold loan app before assuming credit history is a hard requirement can open a door that unsecured lending simply won’t, at least not yet.
What About Becoming an Authorized User or Co-Applicant?
Worth considering if the option exists within your own family. Being added to an existing credit card as an authorized user, or co-applying on a loan with someone who already has an established history, can help a thin file gain some early activity.
This isn’t a shortcut that works in isolation, though, since it still depends on responsible use by whoever holds the primary account.
Habits That Build a Track Record Faster
A few consistent habits matter more here than any single product choice:
- Paying every bill in full and on time, since even one missed payment early on sets the file back considerably.
- Keeping credit card usage well below the limit rather than running it close to capacity every month.
- Avoiding multiple applications within a short window, since each one leaves a mark that can look like desperation to a lender reviewing the file later.
- Checking your credit report periodically, simply to confirm the activity being reported actually matches what you’ve done.
Mistakes New Borrowers Make Early On
- A lot of people apply to several lenders at once hoping one says yes, not realizing each inquiry can quietly work against them.
- Some take on a bigger loan than needed purely to look more serious as a borrower, then struggle with repayment and damage the very file they were trying to build.
- Others get a secured card and let it sit unused, missing the point that activity, not just possession, is what builds a record.
- And plenty never check their own report until they need credit urgently, missing errors that could have been fixed much earlier.
The Real Starting Point
Building a credit profile from nothing isn’t about finding one clever shortcut. It’s about generating a small, consistent, honest track record and letting it grow steadily from there.
Whether that starts with a secured card, a modest loan, or an asset-backed option that doesn’t need history at all, the discipline behind repaying on time matters far more than which product gets you started.