Most first-time buyers take the first rate a lender offers, then pay for that choice for 30 years. For most people, LendingTree is the best of the mortgage comparison apps for first-time buyers, because it puts several real lender offers on one screen for free.
Below: a quick chart, honest flaws for all 10 picks, and a plan that protects your credit.
Quick Comparison Chart: What Each App Actually Does
Not every tool here compares lenders; some just get you ready to shop. This chart sorts the mortgage comparison apps for first-time buyers by the job they really do.
| App | Type | Credit check to see offers | Best for |
|---|---|---|---|
| LendingTree | Marketplace app | Soft check first | Seeing many offers fast |
| Own Up | Marketplace (mobile web) | No hard check | Shopping with less pressure |
| Zillow | Home search + lender | Full review for preapproval | Setting a real budget |
| Bankrate | Rate tables + lender network | None to view tables | Checking rates by ZIP code |
| Rocket Mortgage | One lender | Full review for preapproval | A benchmark quote |
| Redfin | Home search tied to Rocket | Through Rocket | Bundle savings |
| Better | One online lender | Full review to apply | Fast online approval |
| Experian | Credit app | None | Checking your FICO score |
| Credit Karma | Credit app | None | Spotting report errors |
| Down Payment Resource | Assistance search | None | Finding grants |
Key takeaway: Pair one marketplace, one direct lender and one credit app.
The 10 Best Mortgage Comparison Apps for First-Time Buyers
Here’s how the mortgage comparison apps for first-time buyers stack up on four things: lender choice, credit impact, sales calls, and help with small down payments. Rankings draw on company disclosures, app store listings and real owner complaints.
1. LendingTree: Best Overall for Side by Side Offers
Among mortgage comparison apps for first-time buyers, LendingTree is the closest thing to a true comparison tool. The free app holds a 4.8 rating from about 38,000 reviews, takes up roughly 62 MB, and lets you save and compare personalized offers from its lender network.
Picture this: you fill in one form on your lunch break, and by dinner you have several quotes to stack against each other. That gives you real bargaining power when you call a lender back.
Here’s the catch:
- The phones ring. A lot. One App Store reviewer counted 21 calls within minutes of submitting their details.
- First quotes can shift. Early numbers often assume a strong profile and change after a full application.
- Partners only. You see LendingTree’s network, not the whole market.
Who Should Skip This: Anyone who can’t handle a burst of calls and emails during a busy work week.
2. Own Up: Best for Shopping Without Sales Pressure
Own Up is the calmest of the mortgage comparison apps for first-time buyers, built for people who want to compare offers quietly. It promises no hard credit check to see offers and no sales pressure, and one recent review lists a 580 minimum score and 3% minimum down payment. It’s free and paid for by lenders.
The truth is, this one is in transition. Experian agreed to buy Own Up in February 2026, saying its network of 40+ lenders will move into the Experian Marketplace.
- No standalone app, so you’ll use a mobile browser.
- It doesn’t publish a full fee schedule, so lender fees and points vary.
- You won’t see every lender or loan type out there.
Who Should Skip This: Buyers who want everything inside one phone app today.
3. Zillow: Best for Setting a Real Budget
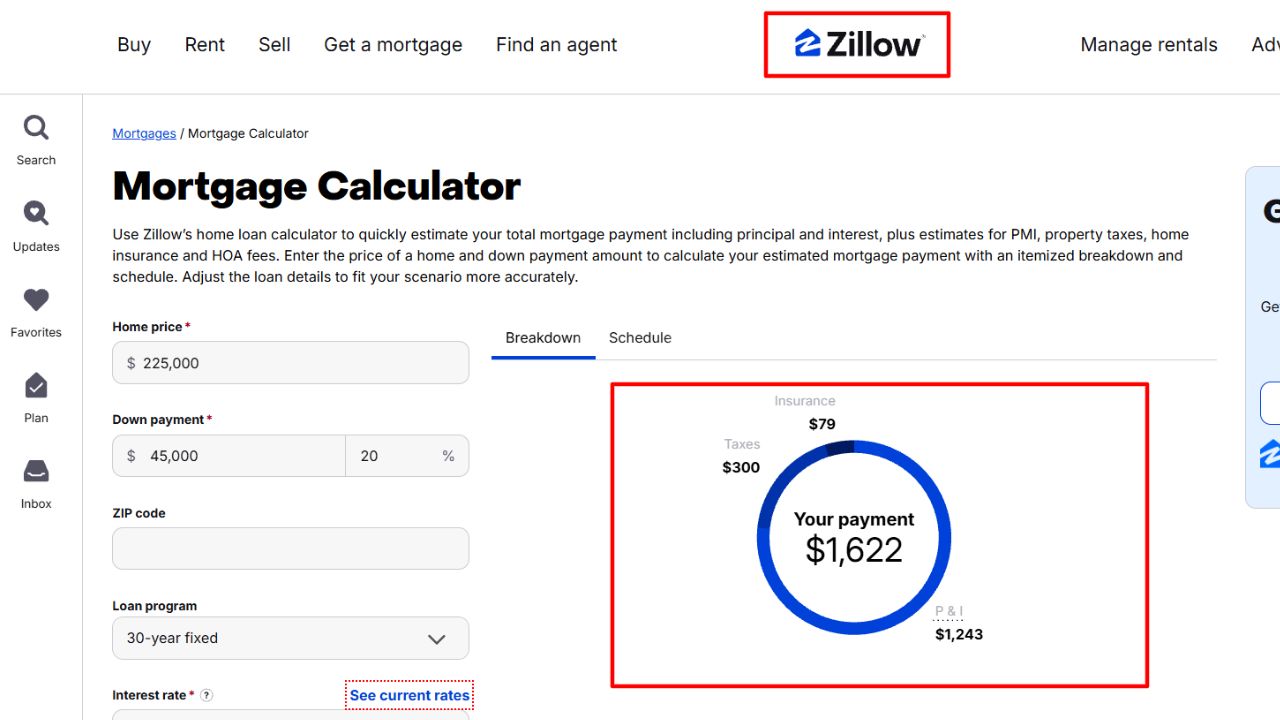
Most first-time buyers start here anyway. Zillow’s BuyAbility tool estimates what you can afford using live rates. Its June 2026 update added a hub that walks you through four steps: budget, search, offer and closing.
Zillow’s own research found only 28% of buyers who planned to finance were preapproved before they started looking. That’s backwards.
A preapproval that counts taxes, insurance, HOA fees and closing costs keeps you from falling for homes you can’t afford. Our mortgage tips for first-time homebuyers cover that budget math in more detail.
On the flip side, Zillow isn’t neutral. Its verified preapproval comes from Zillow Home Loans, and the app is heavy at about 507 MB. BuyAbility is an estimate, not an approval.
Who Should Skip This: Anyone who wants an unbiased rate comparison. Use it to plan, then shop elsewhere.
4. Bankrate: Best for Checking Rates by ZIP Code
Bankrate lets you check rate tables by ZIP code before you share anything personal. It reaches over 100 lenders, and its lender reviews and calculators are easy to follow for a first-time buyer. Its mortgage tools live mainly on the website, so expect to use a mobile browser.
Two real problems:
- Once you fill in the full questionnaire, lenders contact you, and some users say the emails and calls are overwhelming.
- A quote from its network might not be the lowest you can get.
Treat it as a starting point; our guide on how to find the lowest mortgage rates shows what to do next.
Who Should Skip This: Buyers who want one clean app with alerts and saved offers.
5. Rocket Mortgage: Best Benchmark Quote From One Lender
Rocket isn’t a comparison app; it’s a direct lender. But a first-time buyer needs one big lender quote to measure marketplace offers against, and Rocket is easy to get.
The app is rated 4.9 from about 181,000 reviews, takes about 185 MB, and needs iOS 18 or later. You can apply, upload pay stubs, and track every step.
- It shows Rocket’s rates only.
- One reviewer says it asks for a password and a text code every single time you open it.
- Another says the points feature works better on the website.
Who Should Skip This: Anyone hoping one app will do the shopping for them.
6. Redfin: Best If You’ll Use a Redfin Agent
Rocket now owns Redfin, and the two launched a bundle in May 2026. New clients who buy with a Redfin agent and finance with Rocket can get a credit of 0.75% of the loan, up to $6,000, in select markets. On a $350,000 loan, that’s about $2,625.
Sounds great. Not always.
A closing credit doesn’t mean you got the best rate, so compare the full cost. It also ties you to two companies in certain markets only.
Who Should Skip This: Buyers who already have an agent they trust.
7. Better: Best for Fast Online Approval
Better is a direct online lender built for speed. It offers 3% down on conventional loans, 3.5% on FHA and zero down on VA, with minimum scores of 620 and 580. Its One Day Mortgage can issue a loan commitment within 24 hours if your documents are ready, and there’s an AI voice helper named Betsy.
The best part? Rates tend to be strong, though its average origination fee runs about $2,910, a bit above the national average.
- Higher than average complaints filed with the CFPB, mostly about communication and servicing.
- No USDA, renovation or construction loans.
Who Should Skip This: Rural buyers who need a USDA loan.
8. Experian: Best for Checking Your FICO Score First
Checking your own score never hurts it. Experian’s free app shows a FICO Score 8 based on your Experian report. With Own Up joining Experian, mortgage offers are expected inside the same marketplace.
- Mortgage lenders often use older FICO versions, so your number may not match theirs.
- The app pushes card and loan offers hard.
Who Should Skip This: Buyers who already have a lender’s credit report in hand.
9. Credit Karma: Best for Spotting Credit Report Errors
Credit Karma shows free VantageScore 3.0 scores from TransUnion and Equifax. Its real value is the reports: a wrong late payment on one bureau can raise your rate, so fix it before you apply.
Now, you might be wondering why the score doesn’t match your lender’s. Most lenders use FICO, not VantageScore. The app also earns money from advertisers, so its offers aren’t a neutral list.
Who Should Skip This: Anyone who wants an actual mortgage quote. This is prep work only.
10. Down Payment Resource: Best for Finding Down Payment Help
This is the tool most lists of mortgage comparison apps for first-time buyers leave out. Down Payment Resource tracked 2,833 homebuyer programs as of October 1, 2026, and 2,110 of them help with down payment or closing costs. The average benefit is about $18,000, and 239 programs are grants you don’t pay back.
Big deal for first-time buyers. About 62% of programs require first-time buyer status.
- Many programs have income and price limits and can run out of money.
- Only certain lenders take part, which narrows who you can compare.
Who Should Skip This: Buyers with a 20% down payment already saved.
How to Compare Mortgage Offers Without Hurting Your Credit
The best mortgage comparison apps for first-time buyers only work if you shop the right way. This four step plan keeps the damage to your credit small.
- Check your own score first. Use Experian or Credit Karma. It doesn’t count as a lender inquiry.
- Get all quotes within 14 days. Newer FICO versions treat mortgage checks within 45 days as one inquiry, but older versions that many lenders still use allow only 14 days.
- Compare Loan Estimates, not ads. A lender must send this three page form within three business days of your application. Look at the APR, the origination charges in Section A, and any points.
- Ask about a rate lock. A good rate means nothing if it expires before closing.
Here’s why it matters. Freddie Mac’s average 30 year rate was 7.32% on October 22, 2026. On a $350,000 loan, that’s about $2,404 a month for principal and interest.
| Rate | Monthly payment | Extra cost over 30 years |
|---|---|---|
| 7.32% | $2,404 | About $21,320 more |
| 7.07% | $2,345 | Baseline |
A quarter point gap costs about $59 a month. Small number. Huge total.
If your file is messy, with self employment or thin credit, a broker can shop wholesale lenders for you. Our page on professional mortgage broker services explains when that makes sense.
That Brings Us to the Biggest Mistake People Make
They treat a rate from mortgage comparison apps for first-time buyers like a promise. It isn’t. Until you see a Loan Estimate, that number is an ad.
Good news: since March 5, 2026, the Homebuyers Privacy Protection Act has limited credit bureaus from selling “trigger leads” when you apply for a mortgage, unless you opt in or already bank with that lender. But if you ask a marketplace to match you with lenders, those lenders can still call. That’s what you signed up for.
Bottom line: Pick your tools on purpose, and don’t hand your phone number to five marketplaces at once.
Frequently Asked Questions (FAQs)
Do mortgage comparison apps hurt your credit?
Not at first, and that’s a big reason mortgage comparison apps for first-time buyers are worth using. Most use a soft check or none at all to show offers. A hard check comes when you apply with a lender.
Are mortgage comparison apps free?
Yes, for buyers. Marketplaces get paid by lenders or advertisers, which is why calls follow.
How many lenders should a first-time buyer compare?
Aim for at least three Loan Estimates. Many buyers mix one marketplace offer, one big lender and one local credit union.
What credit score do first-time buyers need?
FHA loans usually allow 580 with 3.5% down. Conventional loans usually start around 620.
Final Thoughts
The right mortgage comparison apps for first-time buyers won’t pick a loan for you, but they’ll stop you from overpaying. Start with LendingTree or Own Up for offers, add Rocket or Better for a benchmark, and check Down Payment Resource for free money. Then get three Loan Estimates in the same two weeks, and let lenders compete.